How is revenue from defence contracts recorded by companies, and what can different forms of revenue recognition tell us about a programme’s financial performance?

How is revenue from defence contracts recorded by companies, and what can different forms of revenue recognition tell us about a programme’s financial performance?
Growth in sales, profit, and programme revenue are not always the straightforward reflections of production and deliveries that they seem to be. For instance, in the second quarter of 2026, revisions to contract estimates added USD 375 million to Lockheed Martin’s operating profit – 15% of the reported total.
My previous article examined how defence contracts distribute financial risk between governments and contractors. However, another important consideration is how the financial performance of these contracts is reflected in a company’s accounts after a contract is established. This is known as ‘revenue recognition’.
To do this, accounting divides a contract into ‘performance obligations’ – essentially the distinct goods or services that a contractor has promised to provide. A contract may contain one obligation or several, depending on whether those promises are separately identifiable.
Revenue associated with these obligations is generally recognised either ‘over time’, as work progresses, or at a ‘point in time’, such as upon delivery. As an example, much of General Dynamics’ long-term defence revenue is recognised over time, whereas most revenue from its Gulfstream business jets is recognised upon delivery (Gulfstream is a subsidiary of General Dynamics).
A reader who only sees revenue figures may assume that cash is coming in smoothly to the contractor. However, these accounting methods are not necessarily indicative of how payments were made to the contractor in reality. Revenue recognition shows accounting progress, and not necessarily the true flow of cash or final contractual certainty.
Furthermore, long-term revenue recognition requires estimates, and these initial estimates are often adjusted, due to a range of possible factors.
A very recent example is discussed on Lockheed Martin’s quarterly report, where its revisions to profit, which they call ‘profit booking rate adjustments’, added USD 375 million in the first half of 2026, despite mostly highlighting losses it made in this period on the F-16, C-130, and Heavy Lift and Seahawk programmes. The reasons for the losses named were due to either issues with production performance, or delivery/schedule delays.
| Table 1: Lockheed Martin H1 2026 adjustments | |||
| Segment | Implied positive adjustments (USD) | Named negative adjustments (USD) | Net (profit booking rate) adjustments (USD) |
| Aeronautics | ≥295 million (including F-35: +130 million) |
F-16: -125 million; C-130: -95 million |
+75 million |
| Missiles and Fire Control | ≥325 million | None identified. | +325 million |
| Rotary and Mission Systems | ≥235 million | Heavy Lift: -95 million; Seahawk: -80 million |
+60 million |
| Space | ≥130 million | None identified | +130 million |
| Total | ≥985 million | -395 million | +590 million |
Where does the large positive sum come from? An example from the first quarter of 2026: Lockheed Martin reported that it recognised a favourable adjustment to the F-35 of USD 130 million in their Aeronautics segment.
Over the years, these adjustments repeat across the numerous programmes that Lockheed Martin is active in. Eventually, they accumulate hundreds of millions in adjustments, as we can see here. Yet, no single adjustment is dramatic enough such that all of them are listed and discussed every quarter.
In fact, Lockheed Martin have themselves admitted that profit booking rate adjustments can have a “significant effect” on their financial statements, but despite their significance, this disclosure is located on page 18 of an SEC filing that most people will probably not pay attention to.
Another interesting insight can be found in General Dynamics’ Q2 2026 quarterly report, where they discuss a “large, long-term contract with an international customer for tracked vehicles…”. Here, they state that the actual amount of ‘variable consideration’ could be less than what they estimate, which could have a “material unfavourable impact” on their financial results.
‘Variable consideration’ refers to revenue whose final amount remains uncertain, potentially involving modifications, recovery costs, or other uncertain ‘consideration’ (additional adjustments to revenue/costs). Moreover, General Dynamics reports net unbilled receivables of USD 1.3 billion associated with a large international tracked vehicle contract in its Combat Systems segment. These represent revenue already recognised but not yet billed, after accounting for customer advances and progress billings.
From the given information, we can infer that this may be related to the UK’s Ajax family, although General Dynamics does not identify the programme. If the estimates of revenue later worsen, the revenue and profit recognised in earlier years can be later reduced through what is called a ‘catch-up adjustment’ in accounting terms. Whether General Dynamics ultimately receives the additional revenue it currently expects depends on the underlying contract terms and how these uncertainties are resolved.
Importantly, the unbilled receivables do not represent overdue payments. Rather, General Dynamics can record revenue before it is contractually entitled to send the customer the corresponding bill. The actual collection of cash may occur later still, though some payments may already have been received in advance.
A recent example that demonstrates how a ‘catch-up adjustment’ can affect a contract can be seen in Babcock’s Type 31 frigate programme. In June 2026, the company reported a GBP 140 million charge, following revised estimates of the cost to complete the programme, including a GBP 95.5 million reversal of previously recognised revenue.
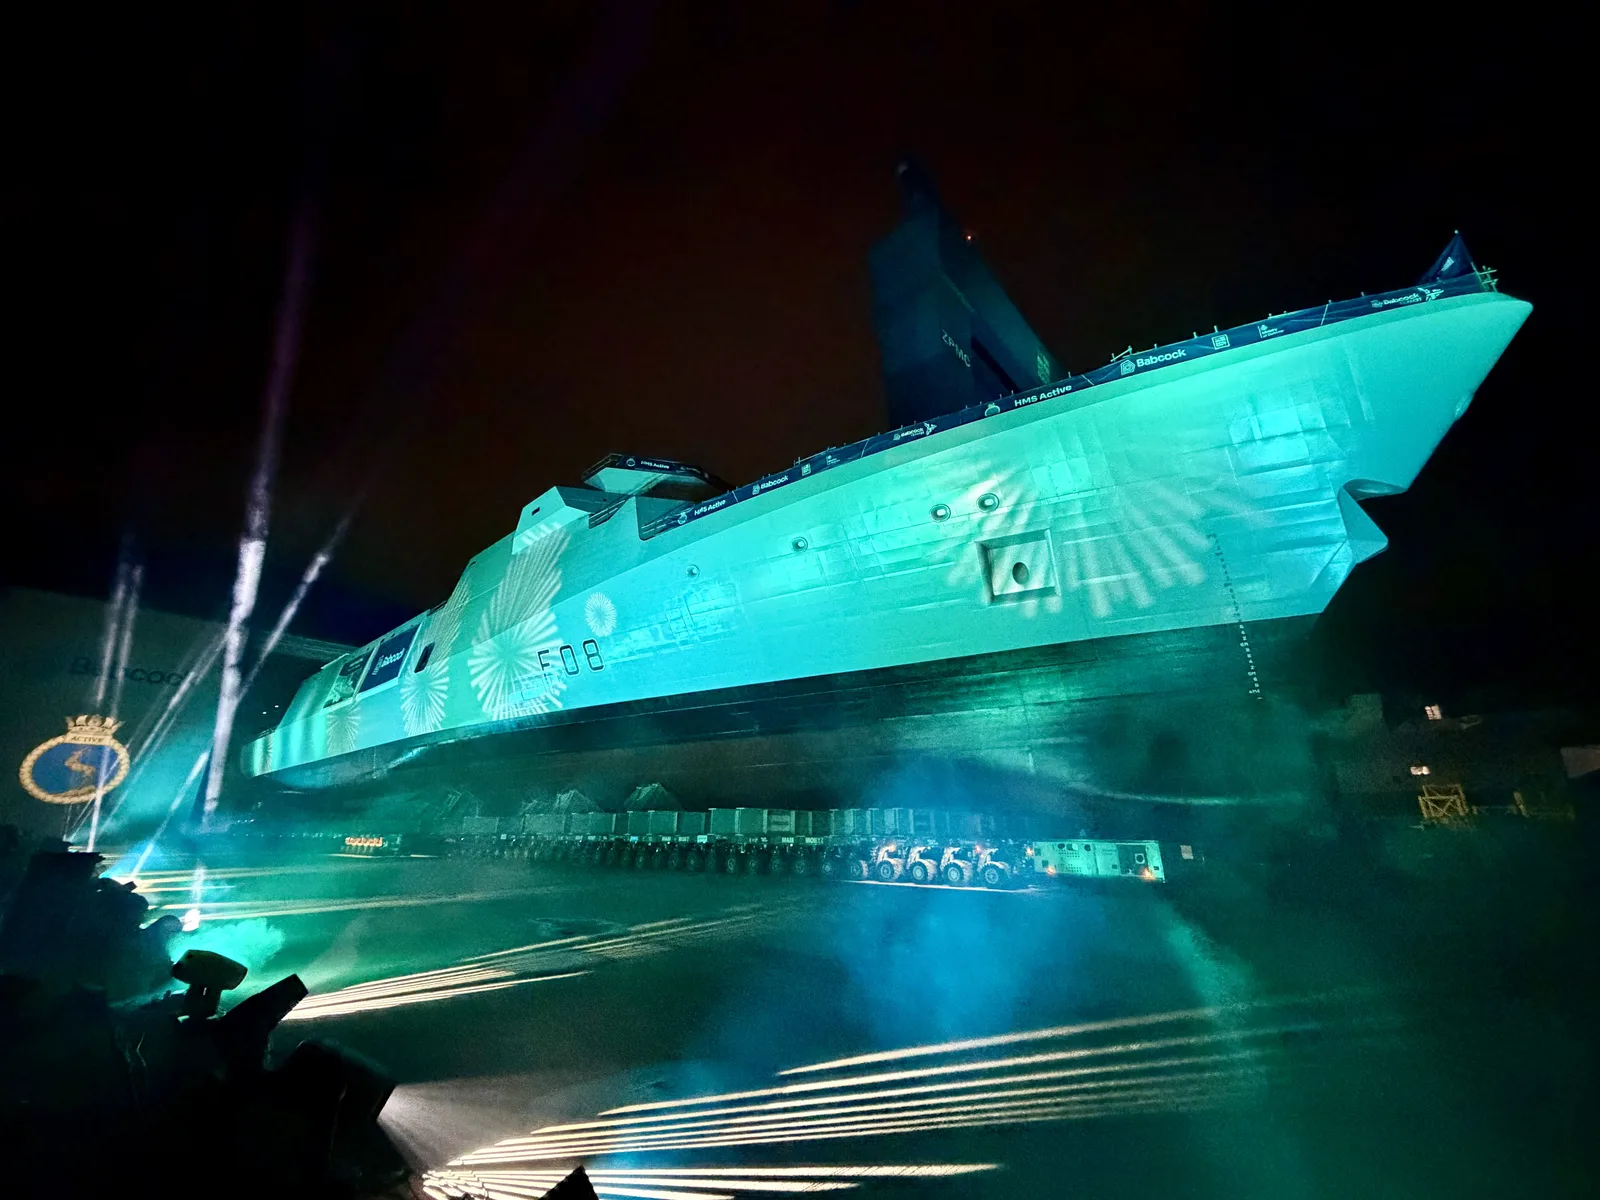
Although this resulted from increasing anticipated costs, unlike the Ajax case of potentially reduced contract revenue, this shows how revisions to long-term contract estimates can erode revenue already recorded in earlier periods.
The examples of Lockheed Martin, General Dynamics, and Babcock illustrate how reported revenue and profit do not always directly reflect production, deliveries, or cash received. Changes in estimates can substantially alter financial results, sometimes even reversing revenue already recognised in previous years.
This does not make financial statements misleading, but it means that headline figures alone cannot provide a complete picture of a defence programme’s financial performance. Understanding the financial reality of a contract is often visible only after looking into the less prominent disclosures behind those figures.